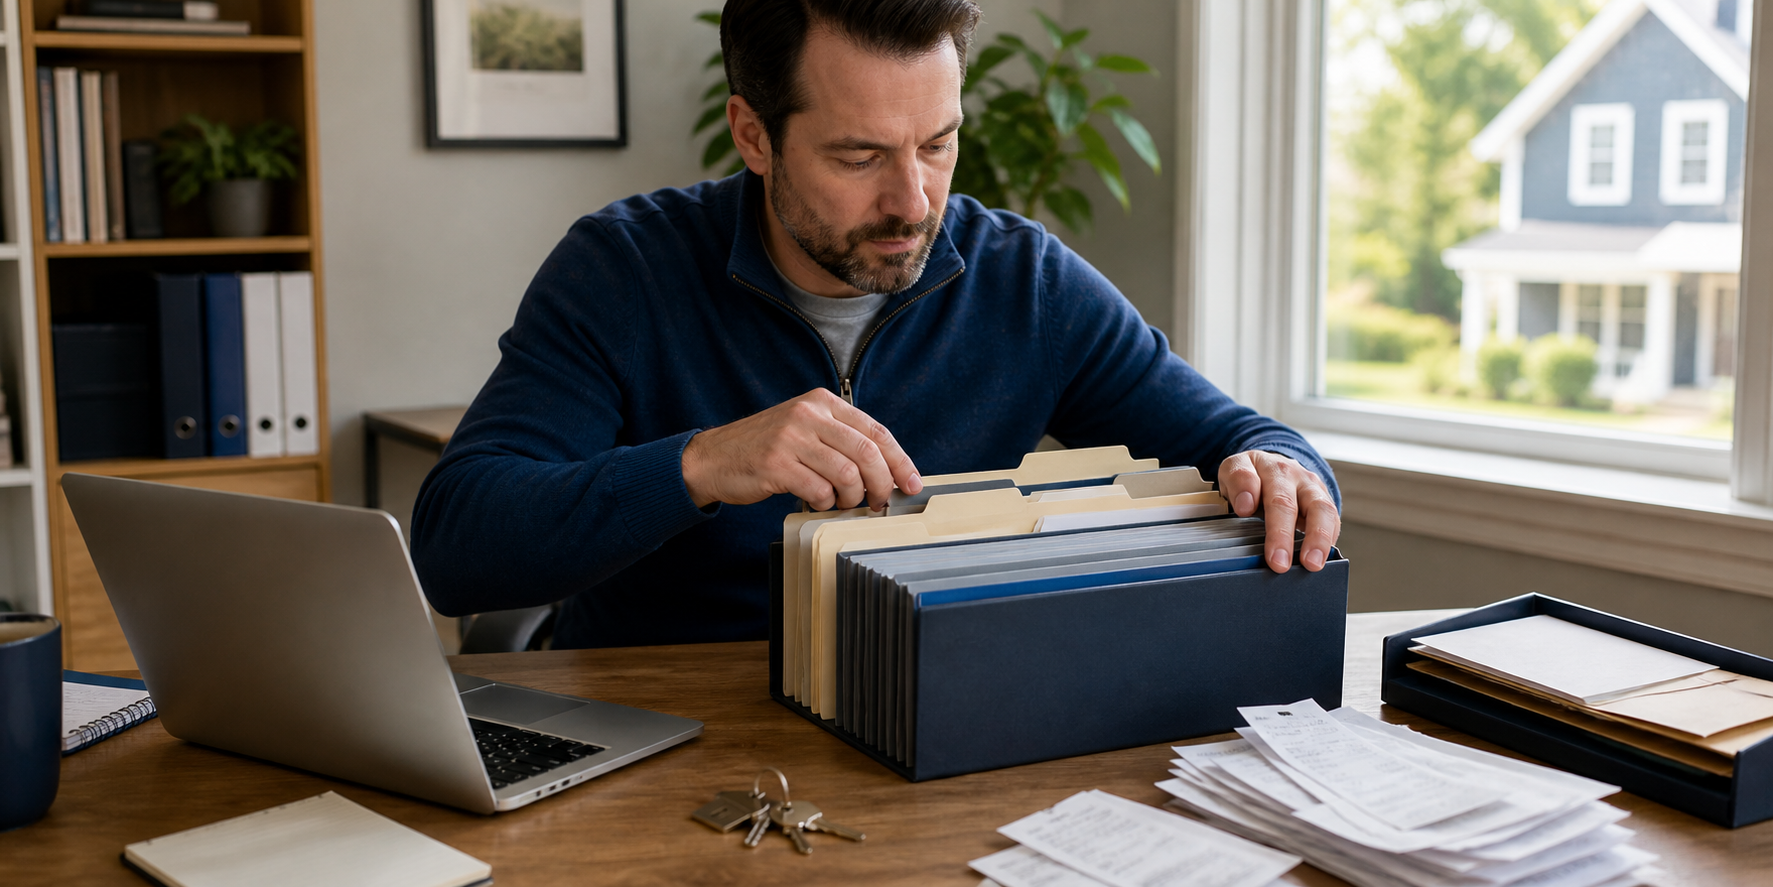
Rental real estate rewards organized records. The value of that system may not be obvious every month, but it becomes critical during tax preparation, a sale, a refinance, a lender request, an insurance claim, or an examination.
The IRS permits a recordkeeping system suited to the activity as long as it clearly shows income and expenses and supports items reported on the return. The best system is therefore not necessarily complicated. It is consistent, property-specific, secure, and designed to preserve the history of the asset for as long as that history matters.
Acquisition and ownership records
Start the permanent property file when the asset is acquired. Closing statements, purchase agreements, title and settlement records, appraisals used for allocation, and documents supporting the allocation between land, building, furnishings, and other assets can affect depreciation and the calculation of gain or loss later.
Keep formation documents, operating agreements, ownership schedules, contribution records, and amendments for entities that hold property. Legal records should be maintained with counsel as appropriate; the accounting file should contain the information needed to record ownership and transactions consistently.
Income and operating records
Every deposit should be traceable to its source. Preserve leases, rent rolls, platform statements, management statements, application or pet fees, parking or laundry income, insurance proceeds, security-deposit activity, and other receipts. A bank deposit alone may not explain what the amount represents or which property earned it.
- Invoices, receipts, and payment evidence for repairs, maintenance, supplies, utilities, and services
- Property-management statements, contracts, and management-fee calculations
- Insurance policies and premiums, property-tax bills, permits, and registrations
- Mileage and travel records with date, destination, business purpose, and supporting expenses
- Vendor forms, contractor records, payroll information, and year-end reporting support when applicable
- Property-level bank and credit-card statements tied to reconciled accounting records
Repairs and improvements need separate histories
The federal tax treatment of a repair can differ from an improvement. IRS Publication 527 explains that an improvement generally must be capitalized when it results in a betterment, restoration, or adaptation to a new or different use, subject to other rules and possible safe harbors.
Keep contracts, invoices, permits, payment evidence, placed-in-service information, and a description of the work. Photographs can provide useful context, but they do not replace cost documentation. Maintain improvement records separately because they may affect basis and depreciation years after the work is completed.
Financing, escrow, and disposition records
Retain original loan documents, refinance and modification agreements, settlement statements, amortization schedules, lender statements, and year-end interest forms. Track how borrowed funds were used when that use may affect the treatment of interest.
When the property is sold or otherwise disposed of, preserve the contract, closing statement, selling expenses, depreciation history, improvement schedule, and records supporting adjusted basis. IRS guidance generally calls for property records to be kept until the period of limitations expires for the year of disposition, which can make the relevant recordkeeping period much longer than three years.
Personal use, short-term use, and local obligations
Rental homes with personal use or short-term stays may require additional detail. Maintain calendars showing rental, personal, and maintenance days; booking-platform activity; lodging or occupancy tax filings; licenses; and jurisdiction-specific records. Rules vary by location and may change, so owners should confirm the requirements for each property.
Keep records in a secure digital system with consistent file names, limited access, and a backup. Sensitive tenant, owner, and taxpayer information should not be sent through ordinary email when a secure portal or approved system is available.
Harbor perspective
Where this fits in a year-round relationship
Harbor helps rental owners build a repeatable property-level system that connects source documents, reconciled books, fixed-asset and improvement records, tax preparation, and owner decision-making. The goal is to organize records when they are created—not reconstruct them years later.
Official resources
Continue with primary guidance
This resource is general educational information and is not tax, legal, investment, or accounting advice for any person or entity. It does not establish a client relationship, provide assurance on financial information, or guarantee a tax or business outcome. Rules and guidance may change. Consult qualified professionals who can evaluate your specific facts and current requirements.